Spring, TX Home Insurance
Home insurance for Spring homeowners, compared across multiple carriers by a local independent broker based in nearby The Woodlands.
The Summit Insurance Brokerage of Texas is based in The Woodlands, at 1790 Hughes Landing Blvd STE 400, The Woodlands, TX 77380, just up I-45 from Spring. Our only office is in The Woodlands, and Spring is one of the communities we serve by phone, text, chat, and email. We'll explain your options in plain English and quote your coverage with several carriers so you can compare price and protection side by side.
What Spring Homeowners Should Know About Home Insurance
One "Spring," two counties
Officially, Spring is a census-designated place in unincorporated Harris County (62,559 residents in the 2020 Census). In everyday use, "Spring" also covers a much larger area of northern Harris County and part of southern Montgomery County, with Spring Creek forming the county line. Your side of the creek determines your appraisal district (HCAD or MCAD) and the local flood resources you'll use. The Texas Department of Insurance (TDI) also lists location as a pricing factor. We confirm exactly where your property sits before comparing policies.
Flooding: the biggest gap in a standard policy
Two creeks shape the Spring area. Spring Creek runs along the county line, and Cypress Creek runs through the Spring and Klein area before it joins Spring Creek. During Hurricane Harvey in 2017, Cypress Creek saw record flooding from its confluence with Spring Creek upstream to near US 290. The Harris County Flood Control District estimates that about 8,750 homes flooded in the Cypress Creek watershed and about 510 in the Harris County portion of the Spring Creek watershed. The District also says plainly that any watershed in Harris County can flood, because the county is flat, has impermeable clay soils, and gets heavy rain from tropical storms and hurricanes.
Here's what that means for your coverage:
- Most home policies don't cover flooding. TDI lists flood among the risks most policies exclude. Flood coverage is a separate policy.
- New flood policies usually take 30 days to start. The National Flood Insurance Program (NFIP) applies a 30-day waiting period, with limited exceptions such as buying the policy at a mortgage closing. Don't wait until a storm is in the forecast.
- Being outside a flood zone isn't a guarantee. TDI notes that more than half of the homes flooded by Harvey were outside designated flood zones.
Our flood insurance page covers how flood policies work.
Hurricanes and high winds reach Spring too, but TWIA isn't part of the picture
Spring is inland, but tropical systems still cause damage here. During Hurricane Beryl in July 2024, the National Weather Service reported widespread tree and power-line damage across Harris County, with many gusts of 60–70 mph, and an 81 mph gust at the Montgomery County Airport in Conroe.
The Texas Windstorm Insurance Association (TWIA) sells wind and hail coverage only in coastal counties and a small area of Harris County along Galveston Bay. Spring isn't in that area, on either side of the county line. Here, wind and hail are normally covered by your regular homeowners policy, which is why your wind/hail deductible matters so much.
Hail, roofs, and percentage deductibles
TDI explains that home insurance deductibles can be a flat dollar amount or a percentage of your policy limits, and that you might have different deductibles for different coverages. A percentage deductible is easy to underestimate. For illustration only: a 2% deductible on a home insured for $300,000 means you'd pay the first $6,000 of a covered claim.
We show each deductible option in dollars, not just percentages. We also check whether a policy pays replacement cost or actual cash value, which matters a lot on an older roof. TDI recommends replacement cost coverage for full protection.
Foundations, slab leaks, and earth movement
TDI lists earth movement among the risks most home policies don't cover, and foundation or slab damage among common endorsements (optional add-ons). Whether a carrier offers foundation coverage, and under what conditions (for example, a plumbing leak), varies by company, so we compare it for you.
Flood, hail, and foundation questions are worth asking before a storm, not after. Let’s look at your policy.
Get a Home Quote
Coverages We Quote for Spring Homes
Wondering what your deductible actually means in dollars? We’ll walk you through it.
Get a Home QuoteMost Texas home policies combine six coverages. We'll help you set the right limit for each one:
- Dwelling: pays to repair or rebuild your house after a covered loss. See homeowners insurance.
- Other structures: covers detached garages, sheds, and fences.
- Personal property: covers furniture, clothing, and other belongings, with optional extra coverage for jewelry or art.
- Additional living expenses: pays extra costs like rent and food if a covered loss forces you out during repairs.
- Personal liability and medical payments: protects you if someone is hurt on your property. For higher limits, see umbrella insurance.
- Flood insurance: a separate policy that you should consider even outside a mapped flood zone. See flood insurance.
- Endorsements worth asking about: water or sewer backup, foundation or slab coverage, building-code upgrades, and extended replacement cost.
Renting? See renters insurance. Bundling? See home and auto for families and auto insurance. Running a contracting business from home? See contractor insurance, because a homeowners policy may not cover business equipment or liability.
Spring at a Glance
| Item | Details |
|---|---|
| Community type | Census-designated place in unincorporated Harris County. The "Spring" name also covers part of southern Montgomery County. |
| Population (Spring CDP) | 62,559 (2020 Census) |
| Owner-occupied housing (Spring CDP) | 74.4% (ACS 2020–2024) |
| Counties | Harris and Montgomery; Spring Creek forms the county line |
| Appraisal districts | HCAD (hcad.org) · MCAD (mcad-tx.org) |
| Major creeks | Spring Creek and Cypress Creek |
| Official flood maps | FEMA Flood Map Service Center (msc.fema.gov) |
| Harris County draft maps | MAAPnext (draft only; not for insurance decisions) |
| Live rainfall and creek levels | Harris County Flood Warning System (harriscountyfws.org) |
| TWIA windstorm eligibility | No. Spring is outside TWIA's designated catastrophe area. |
Why Spring Homeowners Use an Independent Broker
- More than one option. TDI notes that each insurer has its own underwriting rules, so one company might insure you when another won't. We work with multiple carriers instead of just one.
- Help after a nonrenewal. If your carrier drops you, we look for a replacement in the standard market first and explain fallback options like the Texas FAIR Plan.
- Side-by-side comparisons. We compare deductibles, exclusions, and endorsements, not just price.
- One point of contact for home, auto, flood, umbrella, and business coverage, with an office close by in The Woodlands.
Shopping your home policy with more than one carrier takes a single conversation with us.
Get a Home QuoteSpring Home Insurance FAQ
Is Spring eligible for TWIA windstorm coverage? No. TWIA's designated catastrophe area covers the 14 first-tier coastal counties and the parts of Harris County east of State Highway 146 inside La Porte, Morgan's Point, Pasadena, Seabrook, and Shore Acres. Spring homes on both the Harris and Montgomery sides are outside that area, so wind and hail are normally covered by your homeowners policy.
Do I need flood insurance in Spring if I'm not in a flood zone? Lenders require it in designated flood zones (and some require it elsewhere), but TDI notes that more than half of the homes flooded by Harvey were outside those zones. Most home policies exclude flooding, and new NFIP policies usually take 30 days to start, so get a flood quote along with your home quote.
Does it matter if my Spring address is in Harris County or Montgomery County? Yes. Your county determines your appraisal district (HCAD or MCAD) and local flood resources, and location is one of the factors insurers use to set premiums. Give us your exact address and we'll handle the details.
Can I use the MAAPnext flood maps for my insurance? Not yet. MAAPnext maps for Harris County are drafts and can't be used for insurance or regulatory decisions. FEMA's effective flood maps, available at the FEMA Flood Map Service Center, are still the official maps.
Does homeowners insurance cover foundation problems in Spring? Usually not if the cause is earth movement, which most policies exclude. Some carriers offer foundation or slab endorsements, often tied to specific causes such as plumbing leaks. Terms vary, so we'll compare them for you.
Nearby Areas We Serve
We also serve homeowners in The Woodlands, Tomball, Kingwood, Cypress, and Houston. Spring business owners can see Spring contractors insurance, and Spring drivers can see Spring auto insurance. Contractors can also see our The Woodlands and Houston contractor pages.
Get a Spring Home Insurance Quote
Ready to compare? Call or text 281-803-8179, email teamwork@tsibt.com, or start a home quote online.
The Summit Insurance Brokerage of Texas
1790 Hughes Landing Blvd STE 400, The Woodlands, TX 77380
Serving Spring, The Woodlands, and the greater Houston area.
Coverage, deductibles, and endorsements vary by carrier and policy. This page is general information, not a coverage guarantee. Your policy documents control.
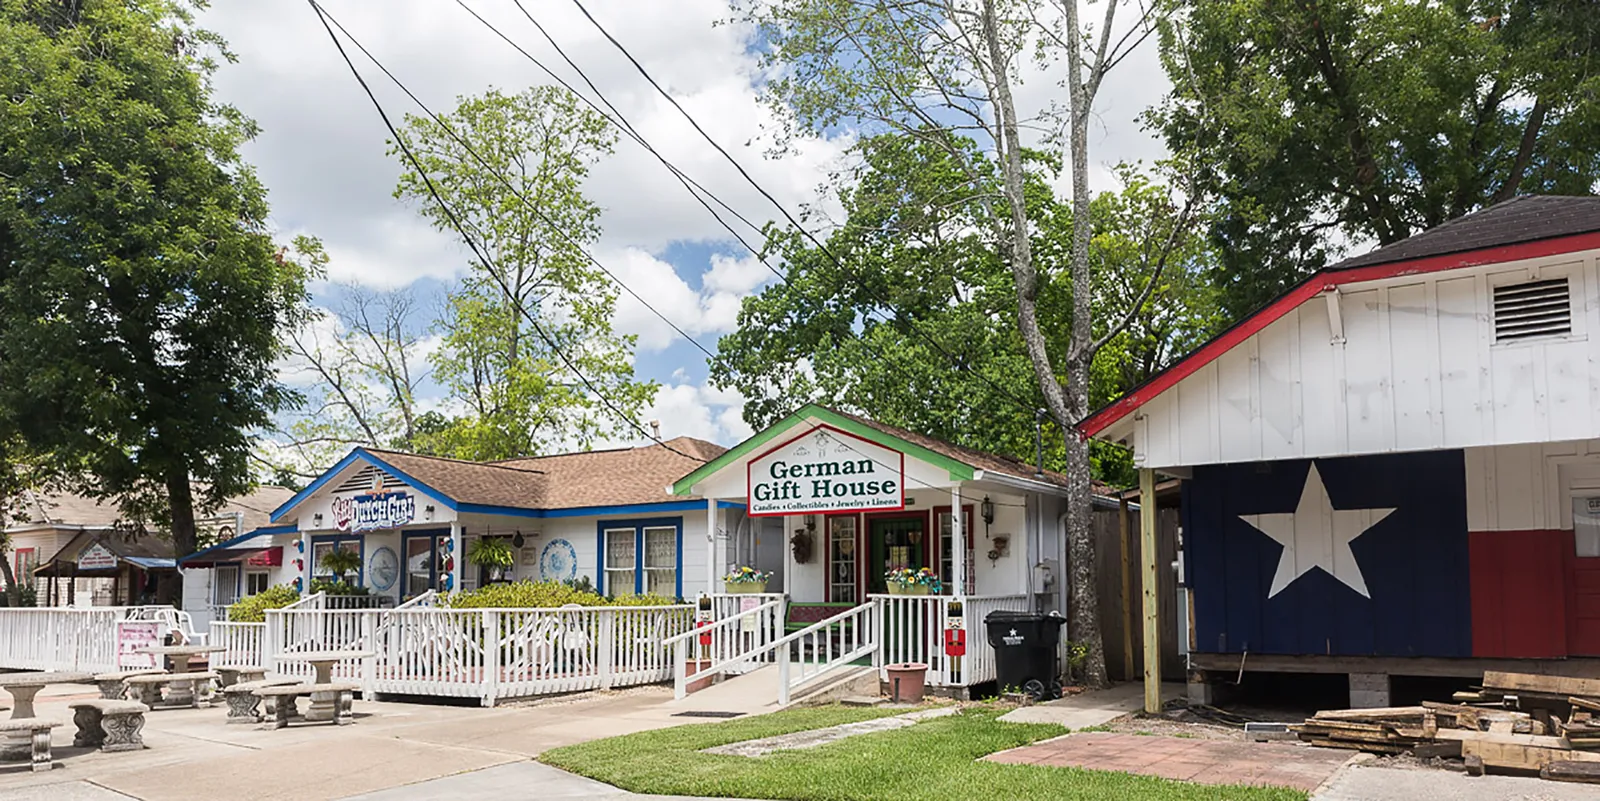
Photo: “Old Town Spring Wiki 5” by Renelibrary, Wikimedia Commons, CC BY-SA 4.0.
More insurance in Spring
What a Client Said
★★★★★
“My meeting with Kris McDaniel at the Summit Insurance Brokerage was exceptional. He explained the different coverage options clearly and helped tailor a homeowner insurance policy for my specific needs. Kris was knowledgeable, answered all my questions, and provided competitive quotes. Overall, a positive and efficient experience. I recommend Kris for anyone looking to purchase a new policy or compare their existing coverage.”